Old Medigap Drug Coverage And The 2026 Part D Decision Seniors Should Not Make Alone
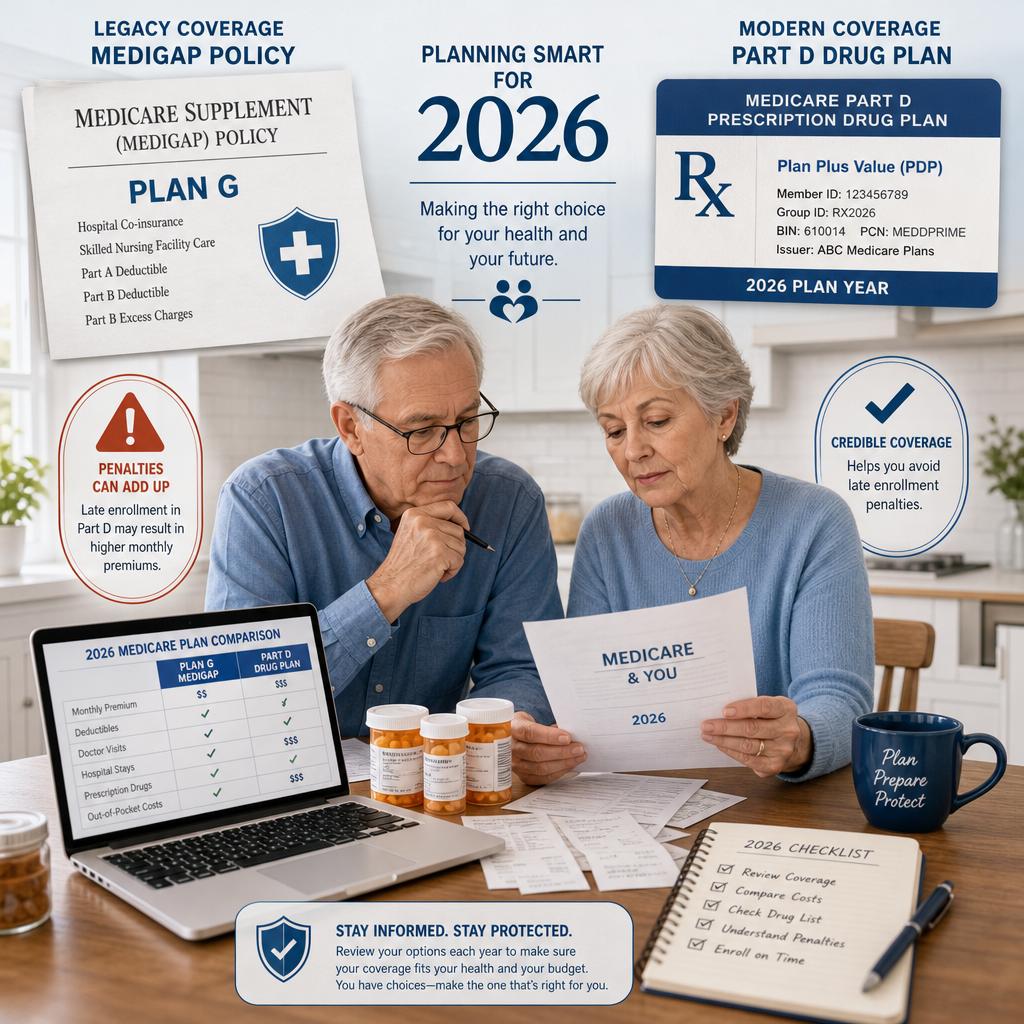
A retired couple can do everything right for twenty years and still face a Medicare decision in 2026 that feels strangely unfamiliar. They kept the same Medicare Supplement policy, paid the premium on time, used the same pharmacy, and avoided annual shopping because the arrangement seemed stable. Then a notice arrives explaining that their old Medigap policy includes prescription drug coverage, while newer Medicare drug plans now operate under a very different cost structure.
That is where the quiet complexity begins. Older Medigap policies with drug coverage are not common anymore, but they still exist. Medicare no longer allows Medigap policies to be sold with prescription drug coverage, yet people who already have one of those older policies may be able to keep it. The complication is that Medicare also says most Medigap drug coverage is not creditable, meaning it may not be expected to pay, on average, at least as much as Medicare drug coverage . In 2026, that distinction can affect not only monthly costs, but also future enrollment rights and penalties.
The Legacy Medigap Drug Benefit Is Not The Same As A Modern Part D Plan
A legacy Medigap drug benefit can feel reassuring because it is attached to a policy the beneficiary already trusts. But Medicare treats prescription drug coverage differently from medical cost-sharing protection. A Medigap policy is designed to help pay some costs Original Medicare does not cover, while Part D is a separate prescription drug program run by private insurers under Medicare rules. When an older Medigap contract still includes drug coverage, the beneficiary is dealing with a historical exception rather than the standard structure most retirees use today.
The word creditable is the hinge. Creditable prescription drug coverage is coverage expected to pay, on average, at least as much as Medicare drug coverage . If the old Medigap drug portion is not creditable, keeping it instead of joining Part D may create a future late enrollment penalty if the beneficiary later decides to move into a Medicare drug plan. This is why a familiar premium is not enough information. The real question is whether the drug benefit protects the beneficiary from future Part D consequences.
Why 2026 Changes Make The Old Arrangement Worth Repricing
The 2026 Part D environment is meaningfully different because covered Part D drug costs are capped at $2,100 for the year. Once a beneficiary reaches that cap, they do not pay a copayment or coinsurance for covered Part D drugs for the rest of the calendar year . For someone taking expensive brand-name drugs, inhalers, oncology medications, or certain specialty therapies, the presence of that cap can change the comparison between an old Medigap drug benefit and a current Medicare prescription drug plan.
That does not mean Part D is automatically better for every person. Drug plan costs still depend on the prescriptions, formulary placement, benefit phase, pharmacy choice, and whether the beneficiary uses a preferred pharmacy or mail order option . Medicare also notes that the first 10 negotiated drug prices take effect January 1, 2026, and beneficiaries must check their own plans to see how those negotiated prices affect them . The practical lesson is that 2026 makes drug coverage more measurable, but not simpler.
The Penalty Risk Is Often Hidden Until It Is Too Late
The Part D late enrollment penalty is not a one-time inconvenience. Medicare describes it as an amount permanently added to the Part D premium when someone goes 63 or more days in a row without Medicare drug coverage or other creditable prescription drug coverage after the Initial Enrollment Period . A retiree who assumes an old Medigap drug rider protects them may be surprised years later if that coverage was not considered creditable.
This can be particularly painful for people whose medication needs were modest for years. A beneficiary might take only a blood pressure pill and a generic statin at 68, then need a costly drug at 74. If they try to enroll in Part D after years of non-creditable coverage, the penalty can follow them for as long as they have Medicare drug coverage. The timing problem is what makes this issue so unforgiving. Medicare decisions made during healthy years often determine flexibility during sick years.
You Generally Cannot Keep Both Drug Benefits
Medicare is clear that a beneficiary cannot have prescription drug coverage in both Medigap and a Medicare drug plan. If someone with an older Medigap policy decides to join a separate Part D plan, Medicare says they should tell the Medigap insurer so the company can remove the drug coverage and adjust the premium . That sounds administrative, but it is really a contract decision. Once the drug portion is removed, getting it back may not be possible in the same way.
This is why the decision should not be handled casually at the pharmacy counter or during a rushed annual enrollment call. The beneficiary needs to know the current Medigap premium, the cost of the drug rider if it can be separated, whether the existing drug benefit is creditable, how current prescriptions price under available 2026 Part D plans, and whether future medication risk argues for moving to the modern Part D structure. A clean answer usually requires looking at both the insurance contract and the medication list.
The Medicare Advantage Angle Can Complicate The Choice Further
Some retirees considering prescription coverage also look at Medicare Advantage plans because most Medicare Advantage plans include Part D drug coverage. That can be attractive, especially when a plan advertises a low or $0 premium. But moving from Original Medicare with Medigap into Medicare Advantage is not merely a drug decision. Medicare Advantage plans may require network providers, referrals, and prior authorization for certain services or supplies, while Original Medicare generally allows broader access to Medicare-enrolled providers who accept Medicare patients .
There is another important boundary. If a beneficiary already has Medigap and joins a Medicare Advantage plan, Medicare warns that they may want to drop Medigap, but if they do, they may not be able to get that Medigap policy back or may have to pay more depending on state rules and their situation . In other words, chasing drug savings without evaluating medical access can create a much larger coverage tradeoff.
How Vista Mutual Reviews This Decision For 2026
A careful 2026 review should begin with the actual medications, not the plan brochure. The name, dosage, frequency, pharmacy preference, and willingness to use alternatives all matter. Medicare specifically notes that generics, biosimilars, pharmacy savings programs, and manufacturer discounts may sometimes lower costs, but those decisions should be checked with the pharmacist and prescribing clinician to confirm the alternative is appropriate . A drug comparison that ignores clinical suitability is not a Medicare strategy. It is a spreadsheet with missing columns.
The second step is to verify the legal character of the existing drug coverage. Is it creditable for 2026 or not? If it is not creditable, how long has the beneficiary gone without creditable Part D coverage? If joining Part D now requires removing the Medigap drug rider, how does that change the supplement premium? If Medicare Advantage is being considered, what doctors, hospitals, authorizations, and out-of-pocket limits come with the plan? Medicare itself reminds beneficiaries to compare coverage annually and notes that October 15 through December 7, 2025 is the annual window to change Medicare health or drug coverage for 2026 .
The peace of mind comes from knowing the decision was tested from every side: drug costs, medical access, contract rights, penalty exposure, and future flexibility. If you or a parent still has an older Medigap policy with prescription drug coverage, do not assume the familiar option is the safest one for 2026. Consult with the Vista Mutual team for a disciplined Medicare review that turns a confusing legacy benefit into a clear, defensible plan.