The 2026 Medicare Aneurysm Screening Referral Rule Seniors Rarely Notice
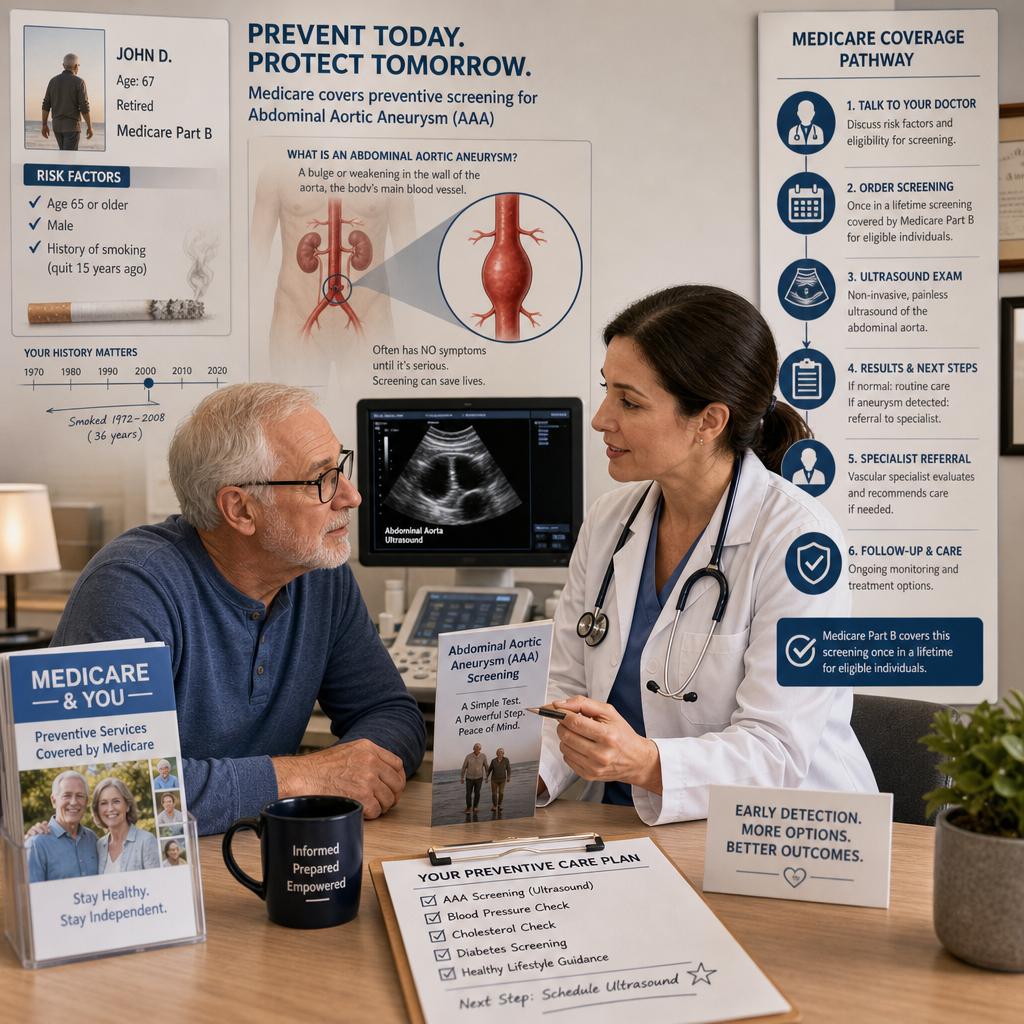
Robert is 67, recently retired, and proud of the fact that he has not smoked in nearly twenty years. At his 2026 primary care visit, his physician asks whether he ever smoked at least 100 cigarettes in his lifetime. Robert laughs because the answer is obvious. Then the doctor explains something Robert had never heard from a television ad, a plan brochure, or a pharmacy mailer: Medicare may cover a one time ultrasound screening for an abdominal aortic aneurysm if the beneficiary is at risk and has the required referral.
That small detail matters. An abdominal aortic aneurysm can develop silently, often without pain or obvious warning signs, and the screening itself is not usually the hard part. The hard part is getting the Medicare pathway right before the test is ordered, scheduled, and billed. Medicare states that it covers an abdominal aortic aneurysm screening ultrasound once for beneficiaries who are at risk, but only with a referral from a doctor or other health care provider. The risk category includes people with a family history of abdominal aortic aneurysms, and men ages 65 to 75 who have smoked at least 100 cigarettes in their lifetime. If the doctor or provider accepts assignment, the beneficiary pays nothing for the screening .
The One Time Benefit Is More Fragile Than It Sounds
The word once is where many Medicare mistakes begin. This is not an annual wellness add on that can be repeated every January, nor is it a general vascular screening for anyone who feels uneasy about heart health. It is a targeted preventive benefit with a defined risk profile. A beneficiary who assumes Medicare will pay simply because the test seems prudent may discover too late that the claim needed a qualifying referral, a qualifying risk history, and a provider billing it as the covered preventive screening rather than as a different diagnostic service.
In an office setting, this often comes down to the quality of the conversation. A patient may tell a doctor, I quit smoking years ago, and leave out the lifetime smoking history because it no longer feels medically relevant. Yet Medicare’s screening rule asks a very specific historical question. A man who smoked casually in college, served in the military when smoking was common, or worked in a setting where smoking breaks were routine may meet the threshold even if he has lived smoke free for decades. The 2026 planning point is simple: a past risk factor can still be the key that opens a present Medicare benefit.
Why Assignment And Visit Coding Still Matter
The screening can be no cost under Original Medicare when the provider accepts assignment, but assignment is not just a casual phrase. Medicare defines assignment as an agreement by the doctor, provider, or supplier to be paid directly by Medicare, to accept the Medicare approved amount as payment in full, and not to bill the patient for more than the applicable deductible and coinsurance . For a preventive service that should cost the beneficiary nothing, that assignment relationship helps protect the patient from avoidable balance billing confusion.
There is another subtle issue. Medicare explains that beneficiaries pay nothing for most covered preventive services when furnished by a provider who accepts assignment, but costs may apply if a preventive service is delivered during the same visit as a non preventive service . That means Robert’s aneurysm screening referral may be clean, but if the appointment also includes evaluation of leg pain, medication changes, or a new symptom that requires medical decision making, the office visit may generate its own cost sharing. The screening benefit may still be covered correctly, while the same day clinical work creates a separate charge.
Original Medicare And Medicare Advantage Treat The Path Differently
Under Original Medicare, the question is usually whether the service is covered, whether the provider accepts assignment, and whether any related diagnostic care falls under ordinary Part B cost sharing. Medicare’s 2026 handbook explains that Part B helps cover medically necessary doctor services, outpatient care, preventive services, durable medical equipment, and other medical services, while also noting that Original Medicare typically leaves beneficiaries responsible for 20 percent of the Medicare approved amount after the Part B deductible when the deductible applies . It also states that Original Medicare has no yearly out of pocket limit unless the person has supplemental coverage such as Medigap, Medicaid, employer, retiree, or union coverage .
Medicare Advantage introduces a different kind of complexity. Advantage plans must cover medically necessary services that Original Medicare covers, but the plan may use networks, referral procedures, and prior authorization rules for certain services or supplies. Medicare also notes that beneficiaries in Medicare Advantage may need to use doctors and providers in the plan’s network and service area for non emergency care, and may need approval before certain services or supplies are covered . For a one time screening, the practical question is not only, Does Medicare cover this? It is also, Which imaging location is in network, does the plan require a referral from the primary care physician, and will the claim be processed as preventive rather than diagnostic?
The Follow Up Can Be More Expensive Than The Screening
The screening ultrasound is only the first decision point. If the scan is normal, the beneficiary may simply keep the record and move on. If the scan finds an aneurysm or an abnormality requiring surveillance, the care pathway may shift from preventive screening into diagnostic imaging, vascular specialist visits, monitoring, and possibly surgical evaluation. That is where beneficiaries often experience surprise. The test that found the problem may have been covered at no cost, but the clinical care that follows can involve ordinary Medicare cost sharing.
Medicare’s outpatient rules illustrate the difference. For many outpatient diagnostic and treatment services in a hospital outpatient department, beneficiaries generally pay 20 percent of the Medicare approved amount for doctors’ services and may also pay a hospital copayment for each outpatient service, with certain preventive exceptions . This is why the site of care matters. A follow up vascular ultrasound at a hospital outpatient department may not feel very different from an ultrasound in an independent imaging center, but the billing structure may be different. A high end Medicare review does not stop at whether a benefit exists. It examines where the care is likely to happen, who bills for it, and how the beneficiary’s plan handles the next step.
The 2026 Planning Question Is Bigger Than One Ultrasound
For many retirees, abdominal aortic aneurysm screening is a good example of Medicare’s broader personality. The program is generous in precise ways and unforgiving in imprecise ones. It may pay fully for a targeted preventive screening when the referral, risk category, and provider assignment are correct. It may also deny or cost share related services when the clinical facts, billing code, site of care, or plan rules move the encounter into another category.
That is why this benefit belongs in a serious 2026 Medicare review, especially for men ages 65 to 75 with any meaningful smoking history, beneficiaries with a family history of aneurysm, and people choosing between Original Medicare with a Supplement and Medicare Advantage. The right plan is not the one with the most attractive headline premium. It is the one that fits the doctors, hospitals, imaging centers, medications, risk profile, travel habits, and likely follow up care of the person using it.
Vista Mutual Insurance Services helps clients slow the decision down before the claim arrives. We look at the Medicare rule, the plan design, the provider network, the Supplement option, the Part D implications, and the real world care pattern behind the benefit. If you want confidence that your 2026 Medicare coverage supports the care you may actually need, Schedule your 2026 Medicare consultation with the Vista Mutual team.