The 2026 Medicare Appeal Representative Mistake Families Should Fix Before A Denial
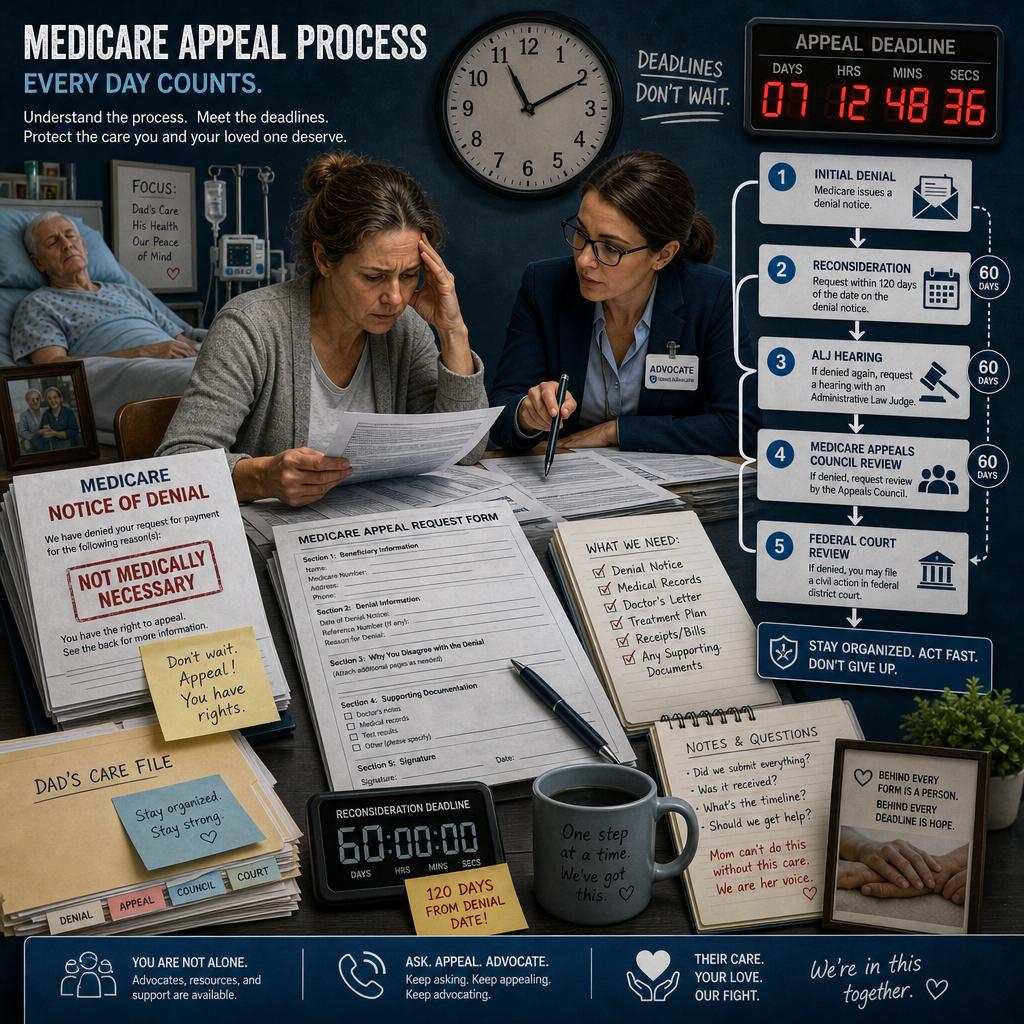
A Medicare denial rarely arrives at a convenient time. It usually appears when a spouse is exhausted, an adult child is trying to interpret plan language after work, or a patient is being told that a medication, rehabilitation stay, home health service, or specialist visit will not be covered the way everyone expected.
For 2026, the overlooked issue is not only whether Medicare gives you appeal rights. It does. The more practical question is whether the right person is prepared to use those rights quickly, accurately, and with the authority to speak for the beneficiary. Medicare says you can appoint a representative to help file an appeal, and that representative may be a family member, friend, advocate, attorney, financial advisor, doctor, or someone else acting on your behalf . That small administrative detail can become the difference between a timely, well supported appeal and a family stuck on hold while a deadline keeps moving closer.
Why The Helper Is Not Always The Authorized Decision Maker
Many families assume Medicare works like everyday medical caregiving. A daughter who drives her father to appointments, fills the pill organizer, and knows every diagnosis may believe she can automatically challenge a denial. A spouse who has always handled household bills may assume the plan will discuss every claim. In real Medicare administration, practical involvement and formal authority are not the same thing.
That distinction matters because Medicare appeals are document driven. The official 2026 handbook states that all people with Medicare have the right to get a decision about payment, coverage of items and services, or drug coverage, and if they disagree with a claim decision, they have the right to file an appeal . Yet having the right to appeal is only the first layer. Someone still must identify the correct notice, understand what type of decision was made, gather medical support, file with the correct entity, and meet the deadline.
This is where families often lose time. They begin with a phone call to the plan, then call the provider, then call the pharmacy, then discover that the plan may not provide detailed information to the helper without proper authorization. By then, the appeal window may be shorter than it appeared. The most sophisticated Medicare planning is not reactive. It anticipates who will be allowed to act when the beneficiary is tired, hospitalized, cognitively impaired, grieving, or simply overwhelmed.
Original Medicare Appeals Start With The Paper Trail
Under Original Medicare, the Medicare Summary Notice is often the starting point. If you disagree with an item or service shown on the MSN, Medicare instructs you to circle the disputed item, explain why you disagree, include your name, phone number, and Medicare Number, keep a copy, and send the appeal to the Medicare Administrative Contractor listed on the notice . The handbook also notes that you must file by the date shown in the MSN, although a late appeal may still be considered if you can show good cause, such as illness, disability, or an accident that delayed filing .
That sounds straightforward until a real bill is involved. Consider a beneficiary recovering from surgery who receives several notices at once: hospital, surgeon, anesthesiology, imaging, durable equipment, and therapy. One line may be denied because of a coding issue, another because Medicare says it lacked documentation, and another because the provider did not bill correctly. If the person managing the papers cannot speak with Medicare, the provider, or a supplemental carrier effectively, the appeal becomes slower and less precise.
Medicare says you will generally get a decision from the Medicare Administrative Contractor within 60 days after it receives the request, and if Medicare covers the item or service, it will appear on the next MSN . That 60 day review period makes the initial filing especially important. A thin appeal that says only I disagree is very different from an appeal that includes the physician’s letter, diagnosis history, medical necessity rationale, and the exact disputed service.
Medicare Advantage And Part D Add A Second Layer Of Timing
Medicare Advantage and Part D appeals introduce another layer because the first decision may come from the plan, not directly from Original Medicare. Medicare Advantage plans must cover medically necessary services that Original Medicare covers, but they may require prior authorization before covering certain services or supplies . The 2026 handbook also explains that a beneficiary or provider can ask a Medicare Advantage plan in advance for an organization determination to find out whether a service, drug, or supply is covered and what the beneficiary will pay .
For prescription drugs, the process has its own vocabulary. Before buying a medication, a person with a Medicare drug plan has the right to request a written coverage determination, which is the plan’s first decision about whether the drug is covered, whether plan requirements are met, or how much the beneficiary pays . If an exception is requested, the prescriber must provide a statement explaining the medical reason the plan should approve it .
This is one reason the 2026 Part D out of pocket cap should not create false comfort. The handbook confirms that yearly out of pocket costs for covered Part D drugs are capped at $2,100 in 2026, after which there is no copayment or coinsurance for covered Part D drugs for the rest of the calendar year . But the word covered is doing serious work. If the medication is not on the formulary, requires prior authorization, fails step therapy, or is processed incorrectly, the cap does not by itself solve the access problem. A capable representative can help push the right request at the right time, but only if the representative is recognized and the prescriber supplies the medical reasoning.
The Fast Appeal Situation Families Must Not Improvise
The highest pressure appeals often involve care ending too soon. Medicare says that if you are getting services from a hospital, skilled nursing facility, home health agency, comprehensive outpatient rehabilitation facility, or hospice, and you believe covered services are ending too soon or discharge is too soon, you can ask for a fast appeal . In these cases, the provider gives a notice explaining how to request the fast appeal, and the notice should be read carefully.
This is not the moment for a family to begin learning who can talk to whom. A discharge appeal may require immediate action, a clear statement of why continued care is medically necessary, and coordination with physicians or facility staff. Medicare identifies the Beneficiary and Family Centered Care Quality Improvement Organization, often called the BFCC QIO, as the independent reviewer for fast appeals when covered services may be ending too soon . The same resource can be contacted when a hospital discharge is disputed or when there are facility quality concerns .
A fast appeal is not a general complaint, and a complaint is not always an appeal. That distinction is easy to miss when a family is frightened. The appeal asks whether Medicare covered services should continue. A complaint may address quality of care, treatment concerns, or service problems. Both may matter, but filing the wrong thing first can cost time.
The One List To Prepare Before A Denial Arrives
A strong Medicare appeal plan is less about confrontation and more about readiness. Before 2026 care becomes complicated, every household should know where the key documents are, who has permission to act, and which insurance path applies. At minimum, prepare the following:
- Confirm who is authorized to speak with Medicare, the Medicare Advantage plan, the Part D plan, providers, and pharmacies.
- Keep copies of Medicare cards, plan cards, the Evidence of Coverage, Annual Notice of Change, drug formulary, and recent Medicare Summary Notices or plan statements.
- Ask physicians to document medical necessity in clinical language, not just in general sympathy for the patient.
- Save denial notices, discharge notices, pharmacy rejection details, itemized bills, receipts, and names of representatives spoken to by phone.
- File appeals by the deadline shown on the notice, and keep proof of submission.
The quiet lesson is that Medicare rights are only as useful as the process used to enforce them. A beneficiary can have excellent doctors, a legitimate medical need, and a sympathetic family, but still experience delay if the appeal begins without documentation or authority.
Choosing Coverage With Appeals In Mind
Most people compare Medicare plans by premium, copay, dental allowance, drug tier, or whether a favorite doctor appears in the directory. Those details matter, but they do not tell the whole story. Medicare Advantage plans can have different out of pocket costs, networks, deductibles, prior authorization rules, and yearly limits on Part A and Part B covered services . Original Medicare may offer broad provider access, but it does not have a yearly out of pocket limit unless the person has other coverage such as Medigap, Medicaid, employer, retiree, or union coverage .
That means appeal exposure is part of plan selection. A person with multiple specialists, expensive drugs, recurring imaging, home health needs, or a likely rehabilitation episode should not choose coverage based only on a low monthly premium. The better question is how the plan behaves when care becomes expensive, urgent, or administratively complex.
Medicare is not simply a card in a wallet. It is a set of rules, notices, deadlines, payer responsibilities, and medical necessity standards. Families who understand that before a denial are calmer when one occurs.
The peace of mind comes from knowing that your plan has been reviewed not just for benefits, but for the real life moments when coverage has to work under pressure. Vista Mutual helps clients evaluate Medicare Advantage, Medicare Supplement, and Part D choices through that practical lens, including the appeal and authorization risks many shoppers never see in a brochure. For careful 2026 planning, Consult with the Vista Mutual team before a denial turns into a deadline.