The 2026 Medicare HMO POS Out Of Network Loophole That Is Not Really Freedom
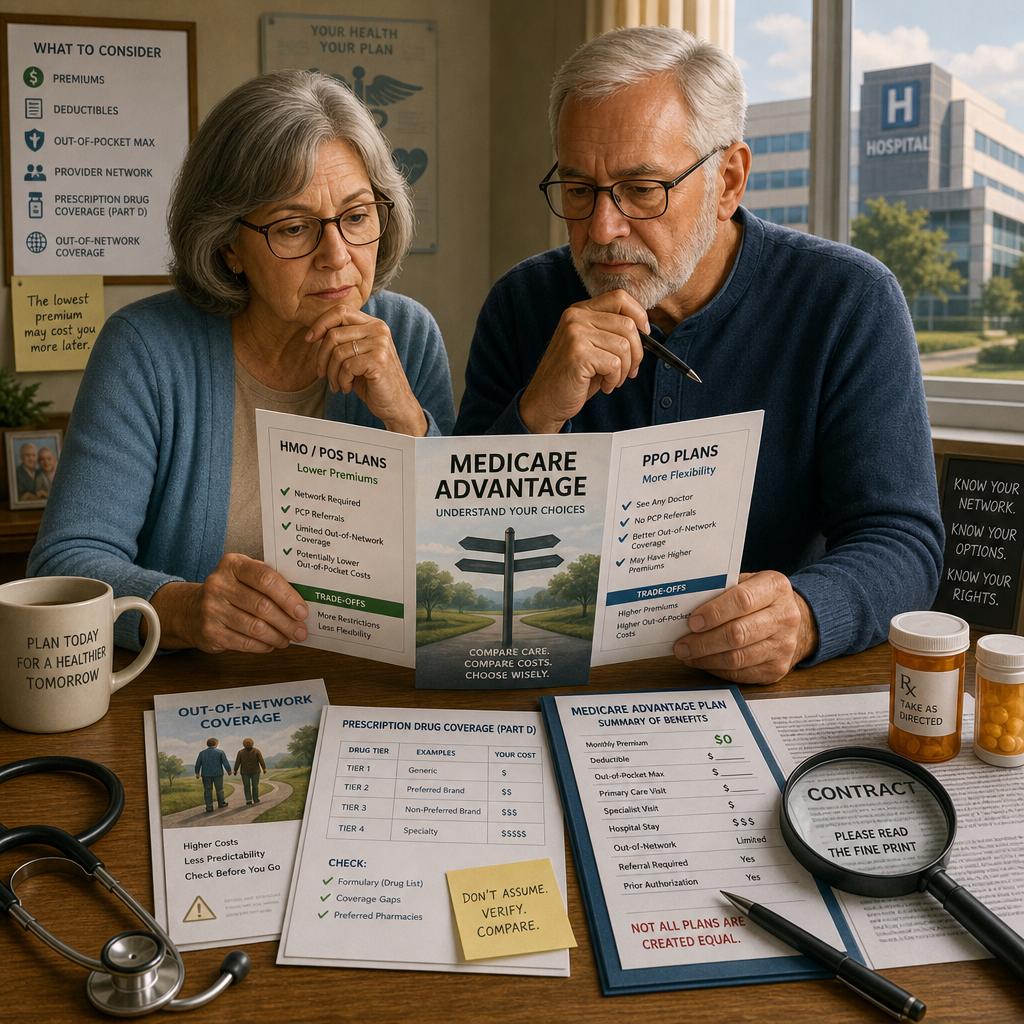
A retired couple comparing 2026 Medicare Advantage plans may see two phrases that sound reassuring: low premium and out of network access. On paper, a Health Maintenance Organization Point of Service plan, often called an HMO POS plan, can look like a compromise between a tightly managed HMO and a broader PPO. In real life, that small phrase can carry consequences that do not become obvious until a cardiologist, orthopedic surgeon, cancer center, or hospital system is outside the plan’s regular network.
This is where Medicare becomes less about slogans and more about contract language. Medicare explains that standard HMO plans generally require members to use doctors, providers, or hospitals in the plan network, except for emergency care, out of area urgent care, or temporary out of area dialysis. Some HMO Point of Service plans may allow certain out of network services, but usually at higher copayments or coinsurance . That word certain is doing a great deal of work.
HMO POS Is Not The Same As A PPO
The most common mistake is assuming that an HMO POS plan behaves like a PPO with a different label. A PPO generally has a provider network but may let you use out of network providers for covered services, usually at a higher cost, as long as the provider agrees to treat you and has not opted out of Medicare . An HMO POS plan is narrower. It begins with the HMO structure, then permits limited exceptions for some out of network care under the plan’s rules.
That distinction matters in 2026 because Medicare Advantage cost comparisons are often reduced to the monthly premium, dental allowance, vision allowance, or Part B giveback. Those features are visible. The harder question is whether your plan will recognize a preferred specialist, outpatient surgical center, or regional hospital as accessible routine care, and if it does, whether the out of network cost is merely higher or financially unrealistic.
The Hidden Risk Is Authorization Not Geography
Many beneficiaries think the HMO POS risk is simply distance. They ask whether the plan will work if they spend a few months with family in another state or whether a well known hospital across the county line is available. Geography matters, but the deeper issue is permission. Medicare notes that Medicare Advantage plans can have different rules for how you get services, including whether you need referrals, whether you must use network providers for non-emergency or non-urgent care, and whether prior approval is required .
A practical example is the retiree who has a local primary care doctor in network but wants a second opinion from a subspecialist at an academic medical center. If the plan treats that specialist as out of network, the member may face higher cost sharing, a referral requirement, an organization determination issue, or a denial if the plan determines that adequate in-network care exists. Medicare makes clear that if a Medicare Advantage plan denies coverage, it must tell you in writing, and you have appeal rights . That protection is important, but an appeal is not the same as timely access to care.
The Drug Coverage Trap Inside HMO Decisions
HMO POS plans also require close attention to prescription drug design. Medicare explains that if you plan to enroll in an HMO and want Medicare drug coverage, you must join an HMO plan that offers Part D drug coverage. If you join an HMO without drug coverage, you cannot join a separate Medicare drug plan . This is one of the most consequential facts many shoppers miss.
That rule can collide with the 2026 Part D environment. Medicare drug coverage has a yearly out of pocket cap of $2,100 for covered Part D drugs in 2026, after which the member owes no copayment or coinsurance for covered Part D drugs for the rest of the calendar year . But that cap only helps when the medication is covered under the plan’s drug benefit. A low premium HMO POS plan with weak formulary coverage for your actual medications can still be a poor fit, even if it looks attractive on the medical side.
What To Read Before You Trust The Brochure
The brochure rarely tells the whole story. Medicare tells beneficiaries in Medicare Advantage plans to review the Annual Notice of Change and Evidence of Coverage each year. The Annual Notice of Change explains changes in coverage, costs, and other items effective in January, while the Evidence of Coverage gives details about what the plan covers and what you pay . For 2026, these documents are not optional reading for anyone considering an HMO POS plan.
A serious review should focus less on whether the plan says out of network and more on how the plan operationalizes that promise. Before enrolling, ask these questions:
- Which out of network services are actually covered under the POS feature, and which require prior authorization or referral?
- Are my key specialists, hospitals, outpatient surgical centers, imaging centers, and pharmacies in network for 2026?
- If I use an out of network provider, is the cost sharing subject to a separate out of pocket limit or a higher tier?
- Does the plan include Part D drug coverage, and are my current prescriptions covered at pharmacies I actually use?
This is the one place where a written answer matters more than a phone conversation. Medicare recognizes that you or your provider can ask a Medicare Advantage plan in advance whether it covers a service, drug, or supply and how much you will have to pay. This is called an organization determination . For complex care, that step can be the difference between a manageable referral and an expensive surprise.
When HMO POS Can Still Make Sense
None of this means HMO POS plans are inherently bad. For some beneficiaries, they can be an efficient way to combine coordinated local care, predictable in-network costs, and extra benefits not available under Original Medicare. Medicare Advantage plans must cover medically necessary services that Original Medicare covers, although plans may use networks and prior authorization rules, and many offer extra benefits such as dental, vision, hearing, transportation, or over the counter support .
The right question is not whether an HMO POS plan is good in general. The right question is whether it is good for your physicians, your medications, your travel pattern, your diagnoses, and your tolerance for managed care rules. Original Medicare usually lets beneficiaries use any Medicare enrolled doctor or hospital that accepts Medicare patients anywhere in the United States, but it has no yearly out of pocket limit unless paired with other coverage such as Medigap, Medicaid, employer, retiree, or union coverage . Medicare Advantage offers a different bargain: plan rules, networks, and a yearly limit on covered Part A and Part B services.
The most expensive Medicare mistake is often choosing a plan that was reasonable for someone else. Vista Mutual helps clients read the fine print behind the premium, compare provider access, evaluate Part D exposure, and understand whether an HMO POS structure is a smart compromise or a hidden restriction. For peace of mind before the 2026 plan year begins, Schedule your 2026 Medicare consultation with the Vista Mutual team.