The 2026 Medicare Two Cap Problem For Medical Bills And Drug Costs
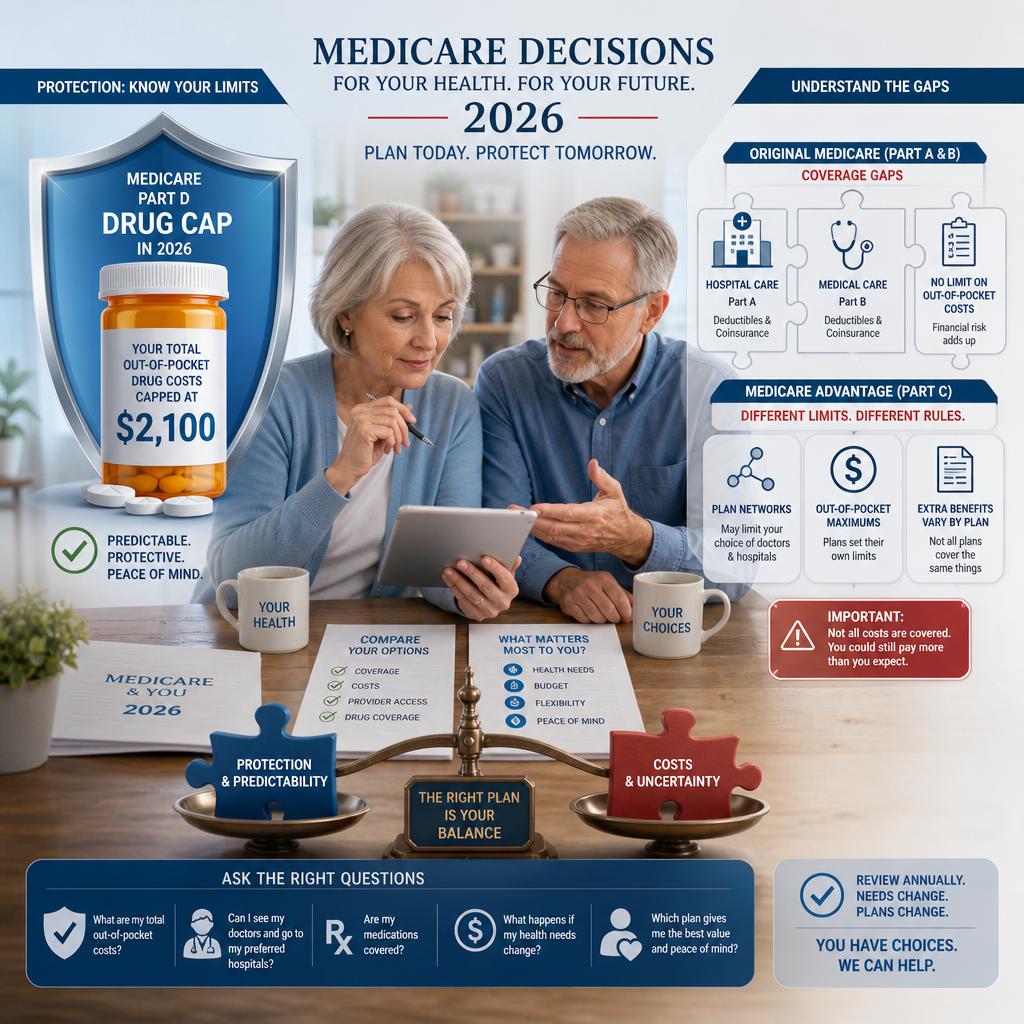
A retired couple can do everything that sounds responsible and still misunderstand their 2026 Medicare risk. Imagine Linda, age 71, who takes two brand name medications, sees a cardiologist twice a year, and is comparing a Medicare Advantage plan with a low premium against Original Medicare with a Supplement and a standalone Part D plan. Her neighbor tells her not to worry because drug costs are capped now. Her plan brochure mentions a yearly out of pocket limit. Both statements may be true, but they are not the same protection.
That distinction matters in 2026. Medicare drug coverage has a major consumer protection: yearly out of pocket costs for covered Part D drugs are capped at $2,100, after which the beneficiary pays no copayment or coinsurance for covered Part D drugs for the rest of the calendar year . At the same time, Medicare Advantage plans have yearly limits for covered Part A and Part B services, while Original Medicare generally has no yearly out of pocket maximum unless a person has other coverage such as Medigap, Medicaid, employer coverage, retiree coverage, or union coverage . The planning mistake is assuming these protections merge into one simple ceiling.
The Drug Cap Is Real But It Is Not A Total Medicare Cap
The $2,100 Part D cap is one of the most meaningful Medicare changes for 2026, especially for beneficiaries taking expensive medications for cancer, autoimmune disease, diabetes, heart disease, or neurologic conditions. It applies to out of pocket spending for drugs covered by your Part D plan. Once the cap is reached, the plan cannot continue charging copays or coinsurance for covered Part D drugs for the rest of that calendar year . For someone who previously faced unpredictable pharmacy bills, that is a significant improvement.
But the word covered is doing a great deal of work. The cap does not mean every medication your doctor writes is automatically protected. Your plan’s formulary, drug tier, pharmacy network, deductible structure, and coverage rules still decide how quickly costs accumulate and whether a prescription is covered at all. Medicare’s 2026 handbook notes that drug costs vary based on whether prescriptions are on the formulary, what tier they are in, which drug benefit phase applies, which pharmacy is used, and whether the beneficiary receives Extra Help . A beneficiary can have a drug cap and still face a formulary exception, prior authorization request, step therapy issue, or pharmacy network surprise before the cap ever becomes meaningful.
Medicare Advantage Has A Medical Limit But It Works Differently
Medicare Advantage plans are often appealing because they package hospital, medical, and usually drug coverage into a single plan design. Many also advertise dental, vision, hearing, transportation, over the counter allowances, fitness memberships, or other supplemental features. Yet the medical out of pocket maximum in Medicare Advantage is tied to covered Medicare services under Part A and Part B, not to every health related expense a retiree might encounter.
The 2026 Medicare materials explain that Medicare Advantage out of pocket costs depend on the plan’s premium, deductible, copayments, coinsurance, network rules, extra benefits, and yearly limit for Part A and Part B covered services . That means Linda’s cardiology visits, outpatient surgery cost sharing, durable medical equipment, diagnostic imaging, and inpatient hospital exposure may count toward the plan’s medical limit when they are covered under the plan’s rules. Her Part D drugs follow the separate drug benefit and the $2,100 drug cap. Dental implants, upgraded eyewear, noncovered services, or care received outside plan rules may be treated differently. The protection is valuable, but it is not universal.
Original Medicare Has Freedom But No Built In Annual Ceiling
Original Medicare remains powerful because it allows beneficiaries to use any doctor or hospital that accepts Medicare anywhere in the United States. For people who travel domestically, split time between states, use academic medical centers, or want fewer network constraints, that flexibility can be decisive. In most cases, Original Medicare also does not require referrals to see specialists, and Medicare’s comparison materials make that contrast clear when setting Original Medicare beside Medicare Advantage .
The tradeoff is financial. Under Original Medicare, beneficiaries generally pay a deductible before Medicare begins paying its share, then pay coinsurance or copayments for covered services. Medicare’s 2026 handbook is direct: there is no yearly limit on what you pay out of pocket under Original Medicare unless you have other coverage, such as Medigap, Medicaid, employer, retiree, or union coverage . That is why a Medicare Supplement decision is not merely a preference about convenience. It is a risk management decision about whether to insure against an open ended medical cost structure.
The Two Cap Problem Shows Up During Real Illness
Consider a beneficiary diagnosed with a serious cardiac condition in February. He fills multiple Part D medications, begins outpatient monitoring, receives imaging, sees specialists, and eventually has a hospital procedure. His drug spending may move toward the 2026 Part D cap. Meanwhile, his medical bills move along a different track. If he is in Medicare Advantage, the relevant question becomes how the plan applies copayments, coinsurance, network status, authorizations, and the plan’s yearly limit for covered Part A and Part B services. If he is in Original Medicare without Medigap or other secondary coverage, the question becomes how much 20 percent coinsurance exposure he can tolerate over a year with no built in ceiling.
This is where a brochure comparison often fails. A low premium plan may be appropriate for one person and risky for another, depending on specialists, hospitals, medications, travel patterns, and tolerance for managed care rules. A Medigap premium may look expensive in a quiet year, then feel like disciplined insurance planning during a year of surgery, infusion therapy, or repeated outpatient testing. The correct answer is not the same for every household.
What Vista Mutual Reviews Before Recommending A 2026 Plan
A professional review should not begin with the plan premium. It should begin with the way your actual life uses Medicare. A credible 2026 analysis looks at your physicians, hospitals, preferred pharmacies, prescriptions, anticipated procedures, travel habits, income related premium exposure, and whether you qualify for help through programs such as Medicare Savings Programs or Extra Help. Medicare itself notes that a trusted agent or broker may be able to help compare plan costs, in addition to resources such as Plan Compare and SHIP .
The most important review points are straightforward, but they require precision: whether your drugs are covered and at what tier, whether your pharmacy is preferred or standard, whether your physicians and facilities are in network, whether referrals or prior authorizations may apply, whether a Medicare Advantage out of pocket maximum protects the services you are most likely to use, and whether Original Medicare should be paired with Medigap to address the absence of a built in annual medical cap. Each issue sounds small in isolation. Together, they determine whether your coverage feels stable or fragile when your health changes.
The Peace Of Mind Comes From Knowing Which Cap Applies
The 2026 Medicare landscape is better in important ways, especially for people with high covered Part D drug costs. But better does not mean simple. A drug cap does not replace a medical cost strategy. A Medicare Advantage medical limit does not eliminate formulary management. Original Medicare freedom does not create an automatic out of pocket maximum. These are separate protections with separate rules.
That is why Vista Mutual treats Medicare planning as a coverage architecture problem, not a shopping exercise. The goal is not to chase the lowest premium or the flashiest extra benefit. The goal is to know, before the year begins, how your doctors, hospitals, prescriptions, and financial risk fit together. If you want a 2026 Medicare review that accounts for the details most people miss, Schedule your 2026 Medicare consultation with the Vista Mutual team.